Money Apps in 2026: 7 Smart Ways to Master Everyday Spending
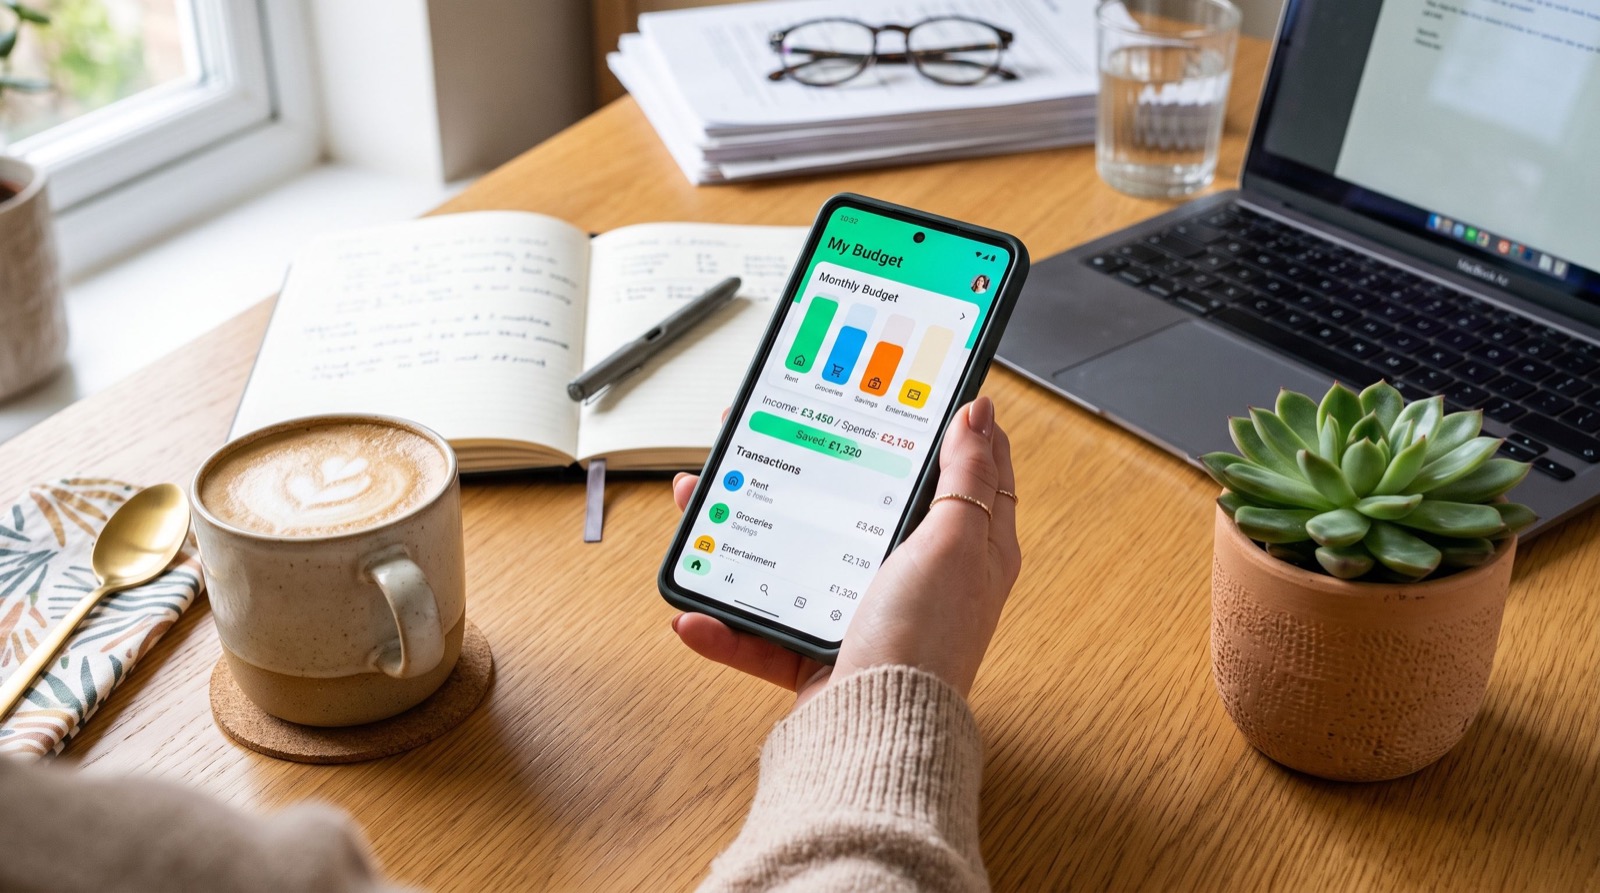
Money apps have quietly become the control room of modern household finance. In 2026, the average person taps a phone dozens of times a day, and a growing share of those taps now touch a budget, a savings goal, or a bill reminder. When you choose the right money apps and use them with intention, you stop guessing where your paycheck went and start directing it on purpose.
This guide walks through a practical, people-first system rather than a hype list. You will learn how to layer tools, avoid common traps, and build habits that stick long after the new-app excitement fades. If you want a curated starting point, the team behind money apps reviews focuses on real-world usability instead of flashy screenshots.
Why Money Apps Matter More Than Ever
Digital payments keep replacing cash, and that shift changes how we perceive spending. A tap feels weightless, so small charges pile up unnoticed. A good app restores that missing friction by showing balances, categories, and trends the moment a transaction clears.
According to the U.S. Consumer Financial Protection Bureau, consumers who track spending regularly report lower financial stress and fewer overdraft surprises. The lesson is simple: visibility drives better decisions, and money apps make visibility automatic.
What separates a great app from a forgettable one?
Great tools reduce effort. They sync accounts securely, categorize transactions accurately, and nudge you at the right moment. Forgettable ones demand constant manual entry and quietly get abandoned within a week.
The Four Core Categories of Money Apps
Before downloading anything, understand the job you need done. Most people benefit from combining two or three complementary tools rather than hunting for a single magical one.
- Budgeting apps that assign every dollar a role and flag overspending early.
- Automated savings apps that move small amounts aside without you noticing.
- Bill and subscription trackers that catch forgotten renewals before they hit.
- Investing and round-up apps that turn spare change into long-term growth.
Comparing the Main Types at a Glance
The table below summarizes how each category fits different goals, so you can match tools to your actual situation instead of chasing trends.
| App Type | Best For | Effort Level | Typical Cost (2026) |
|---|---|---|---|
| Budgeting | Controlling monthly outflow | Medium | Free to $15/mo |
| Automated savings | Building a cushion painlessly | Low | Free to $5/mo |
| Bill tracking | Stopping wasted subscriptions | Low | Often free |
| Investing / round-ups | Long-term wealth building | Low to medium | Free to $8/mo |
A 7-Step System for Everyday Spending
Tools only work inside a routine. Follow these steps in order, and give each one a week or two to settle before adding the next.
- Connect your main accounts. Link the checking account and card you use most so the data reflects real life.
- Set three spending categories. Start small: essentials, flexible spending, and savings. Detail can come later.
- Automate one transfer. Schedule a modest weekly move into savings the day after payday.
- Turn on alerts. Enable low-balance and large-purchase notifications to catch problems in real time.
- Audit subscriptions monthly. Cancel anything you did not knowingly use in the last 30 days.
- Review weekly, not daily. A ten-minute Sunday check beats obsessive hourly glances.
- Adjust and repeat. Treat every month as an experiment and refine your categories.
This rhythm turns scattered tools into a genuine spending strategy. Many readers tell us the weekly review is the single habit that changed their finances most.
Practical Personal Finance Tips That Amplify Your Apps
Software cannot fix habits on its own. Pairing your tools with a few grounded behaviors multiplies the payoff. For deeper reading, these personal finance tips pair neatly with the system above.
Start by giving yourself a 24-hour rule on any non-essential purchase over a set threshold. Sleep on it, and roughly half of impulse buys quietly disappear. Next, keep one “fun money” category guilt-free so the plan feels sustainable rather than punishing.
Finally, protect your accounts. The FDIC recommends enabling two-factor authentication and confirming your bank carries deposit insurance before you link it to any third-party service.
How do I keep my data safe inside money apps?
Use unique passwords, enable biometric login, and review connected apps every few months. Revoke access for any tool you no longer open, because a dormant connection is still a live door.
Reading the Trends Your Apps Reveal
Recording transactions is only step one. The real payoff comes from reading the patterns your data exposes over time. After two or three months, most people spot a recurring leak they never noticed, such as delivery fees, forgotten trials, or weekend splurges.
Set aside ten minutes at month-end to scan your three biggest categories. Ask a simple question of each: did this spending move me toward my goals or away from them? That single reflection, repeated monthly, often reveals hundreds of dollars in painless savings across a year.
Trends also help you plan for irregular costs. Insurance renewals, holidays, and annual subscriptions rarely surprise the person who reviews historical data. Instead of scrambling, you set aside a little each month so the bill arrives already funded.
How long before money apps show useful patterns?
Expect roughly 60 to 90 days. One month is a snapshot; three months reveals genuine rhythms, including the seasonal swings that a single billing cycle cannot capture.
Building a Content and Money Routine Together
Creators and freelancers face a double challenge: managing irregular income while producing constant work. Treat both with the same discipline. The experienced local team behind many productivity workflows recommends batching financial admin the same way you batch content, so neither steals focus from the other.
Set a recurring calendar block for invoicing, expense tagging, and a quick savings sweep. When money management becomes a scheduled task rather than a nagging worry, both your bank balance and your creative output improve.
Frequently Asked Questions
Are free money apps good enough, or should I pay?
For most people, free tiers cover budgeting and bill tracking comfortably. Consider paying only when a premium feature, such as advanced forecasting, clearly saves you more than it costs.
How many money apps should I actually use?
Two or three is the sweet spot. One budgeting hub, one savings automator, and optionally one investing tool. More than that usually creates overlap and fatigue.
Will linking accounts hurt my credit score?
No. Connecting an app to view balances is a soft, read-only link and does not affect your credit. Only formal credit applications trigger hard inquiries.
What is the fastest win for a beginner in 2026?
Automate a small weekly transfer to savings. It requires one setup and then works silently, building a cushion while you learn the rest of the system.
Conclusion: Let the Right Money Apps Do the Heavy Lifting
The best money apps in 2026 do not just record what you spend; they gently steer you toward the life you want. Start with one budgeting tool, automate a single savings transfer, and review your progress weekly. Small, consistent actions compound faster than any dramatic overhaul. Choose your tools with care, pair them with steady habits, and let technology handle the tracking while you focus on living well.